Nonprofit
DMP
Certified

HUD-Approved Housing Counseling Agency

NFCC Member

501(c)(3) Nonprofit




No Obligation
No Pressure


Explore practical tools and resources to help you manage debt, track your progress, and build healthier financial habits.


Always Free
No Obligation
Confidential

For Educational Guidance


Estimated Available Equity

Estimated Monthly Payment Option

Interest Rate Range

Speak with a certified housing counselor to review your situation, questions, and next steps.

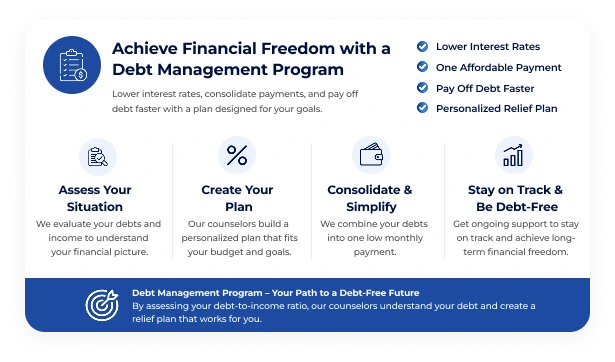
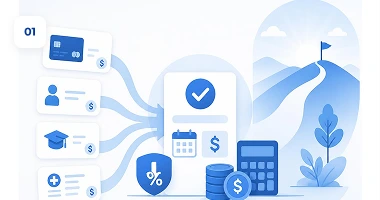
A DMP is a structured repayment plan set up through a nonprofit credit counseling agency. It combines your unsecured debt, credit cards, medical bills, personal loans, into one monthly payment, often at a lower interest rate than you're paying now. It's not a new loan and it's not debt settlement; you still pay back what you owe, just on better terms.

Enrolling in a DMP itself isn't scored as a negative factor. What can affect your credit score is closing the credit card accounts you enroll in, which is usually required so the lower rate doesn't just enable more spending. Closing accounts drops your available credit to zero on those cards, which can spike your credit utilization, 30% of your FICO score, and cause a short-term dip. That utilization typically falls back down as you pay off the enrolled balances, and consistent, on-time DMP payments help your payment history, the single biggest factor in your credit score, over the life of the plan. Results still vary by individual.

Creditors generally expect eligible unsecured accounts to be included, but account eligibility and exceptions can vary. Your counselor will review each debt and explain which accounts can or must be included before you decide whether to enroll.

Most credit card accounts included in a DMP must be closed. Limited exceptions may be available for an essential-use or business card, depending on the creditor and program requirements. Your counselor will explain the rules that apply to your accounts.

Most debt management plans are designed to be completed within three to five years. Your projected timeframe will depend on your enrolled balances, creditor terms, and the monthly payment your budget can support. You may be able to complete the plan sooner by making additional payments.

Your initial credit counseling session is free. If you enroll in a DMP, you may pay a one-time enrollment fee and a monthly administrative fee, both regulated by state law, which is part of why they vary so much agency to agency. Nationally, nonprofit DMP fees typically fall somewhere between $0 and $100 to enroll and $10 to $75 a month, though yours may be lower depending on your state and financial circumstances. Your counselor will tell you the exact number before you enroll, not after.
Debt relief is the umbrella term for any strategy that helps you manage or reduce what you owe: budgeting, debt settlement, bankruptcy, and debt management plans all fall under it. A debt consolidation loan is one specific approach, you borrow new money, usually at a lower rate, to pay off your existing credit card debt. A DMP works differently. There's no new loan and no new debt; your counselor negotiates directly with your current creditors to lower the rates on the unsecured debt you already have, then you repay it through one monthly payment. If your credit isn't strong enough to qualify for a low-rate consolidation loan, a DMP is often the more realistic option, since approval depends on your creditors' terms, not a new lender's credit check. If you're not sure which form of debt relief actually fits your situation, that's exactly what the first counseling session is for.


Private & confidential

Educational guidance

HUD-approved agency

No sales pressure