HUD-Certified

Default Prevention

Nonprofit

Protect your home from reverse mortgage default

Falling behind on reverse mortgage requirements can put your home at risk of foreclosure, but foreclosure isn't automatic and it isn't fast. Credit.org's reverse mortgage default counseling helps homeowners understand the causes of default, including missed property taxes, unpaid homeowners insurance, deferred home maintenance, or occupancy requirements, and what a reverse mortgage foreclosure actually takes to reach. Our HUD-certified housing counselors review your situation as a borrower, explore every available solution, and build an action plan to help you avoid foreclosure and stay in your home.

Credit.org is a nonprofit HUD-certified housing counseling agency and NFCC member.

HUD-Approved Housing Counseling Agency

NFCC Member

501(c)(3) Nonprofit
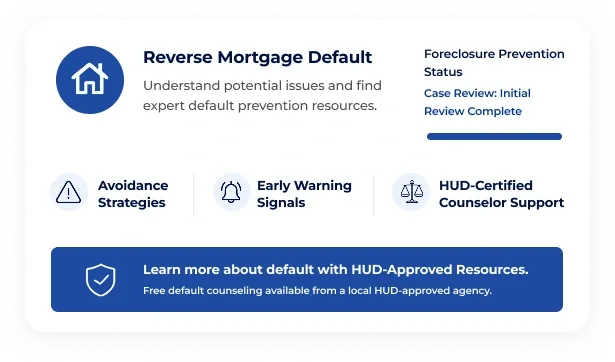
Infographic showing reverse mortgage default prevention resources and counseling.
How we help

What You Gain From

Reverse Mortgage Default Counseling

Expert, judgment-free guidance designed to help you understand your situation, explore every option, and take decisive action to protect your home.
  • Illustration of a home highlighting reverse mortgage default warning signs.

    Understand Why Reverse Mortgage Default Happens

    Learn why a reverse mortgage loan goes into default: unpaid property taxes, homeowners insurance, HOA dues, occupancy issues, or required property repairs. Your counselor helps you understand your obligations as a borrower, review your default notice, and identify what actually needs to happen to stay in your home.
  • Illustration of financial documents representing reverse mortgage default solutions.

    Review Options to Resolve the Default

    During your session, a certified housing counselor reviews your situation and lays out your actual next steps: unpaid property charges, repayment arrangements, extensions, assistance programs, or other resources, and how to communicate all of it to your loan servicer as the borrower of record.
  • Illustration of a protected home representing steps to prevent reverse mortgage default.

    Take Action to Protect Your Home

    Leave your session knowing exactly what to do next. Your counselor helps you prepare questions for your loan servicer, organize your documents, track deadlines, and build a practical plan to resolve the default before it becomes a reverse mortgage foreclosure.
Your path forward

How Default Counseling Protects Your Home

A structured, supportive process designed to give you clarity, options, and a realistic path forward.
  • Step 01

    Identify the Default Risk

    Your counselor starts by reviewing your reverse mortgage loan terms, mortgage insurance status, property tax status, homeowners insurance, and any lender notices you've received as the borrower. Together you pinpoint exactly why default is threatened and what needs attention first.
  • Step 02

    Explore Resolution Options

    We walk you through every available path: repayment plans, HUD's loss mitigation and deferral programs, loan modification requests, forbearance, and alternatives to foreclosure. Your counselor explains what each option actually requires of you as a borrower, so you're comparing real requirements, not just names.
  • Step 03

    Create Your Action Plan

    Together, you and your counselor build a step-by-step action plan for your specific default: communication scripts for your lender, document checklists, payment strategies, and real deadlines you can actually track.
  • Step 04

    Ongoing Support & Follow-Through

    Your counselor stays available after your session to answer questions, help with lender communications, and adjust your plan as your situation changes. You're not handling your loan servicer alone. Your counselor stays with you until the default is resolved, whether that means a repayment plan, a loan modification, or an alternative to foreclosure.
  • No sales pressure. No lender bias.

    Just clear education to help you make an informed decision.

100% Free

No Obligation

No Pressure

Why act now

Benefits of Default Prevention Counseling

Taking action early gives you more options and better outcomes. Our counseling ensures you have expert guidance at every stage.

Immediate Risk Assessment

Within your first session, you'll understand exactly where you stand: what triggered the default risk, how urgent it is, and what stops it, whether that's a repayment plan, a change in who's on title, or an eligible non-borrowing spouse claiming the deferral period.

Compassionate, Judgment-Free Support

Financial hardship isn't a character flaw, and our counselors treat it that way. You won't face judgment or sales pressure here, just a HUD-certified counselor working through your options with you as the borrower, not around you.

Lender Negotiation Guidance

We help you understand how to communicate with your reverse mortgage servicer: what to ask for, what documentation to provide, and what a servicer can and can't legally require from a borrower in default. You'll walk into every conversation knowing exactly where you stand.

Home Protection Strategy

Your counselor helps you build a plan to resolve the default, protect the home equity you have left, and keep your loan balance from growing faster than it has to. There's no template. Your plan depends on how much equity remains, who else is on the loan, and how far behind you are.

Do not wait for a formal notice of default or a foreclosure filing to reach out. HUD's servicing rules give reverse mortgage borrowers real time and multiple offramps before reverse mortgages actually reach foreclosure, but every one of those offramps gets narrower the longer a default sits unaddressed.

Tools & resources

Resources to Help You Take Control

Access free guides, templates, and educational resources designed to help you navigate  the default resolution process with clarity and confidence.

Educational Guides & Worksheets

Explore free guides and worksheets designed to help you build better money habits, reduce debt, improve your credit, and achieve your financial goals.
Download

Video Education Library

Watch short, clear videos explaining the default resolution process, lender communication tips, and homeowner success stories.
Watch

Educational Articles

Expert-written articles on reverse mortgage responsibilities, property tax management, and avoiding common default triggers.
Read

Financial Tools & Resources

Explore financial resources built for borrowers working through a default: a glossary of loan-servicing terms, state unemployment office locations if income loss is part of what triggered your default, and tools to manage debt while you resolve your reverse mortgage.
Access

Financial Calculators

If your default is tied to a broader budget problem, our calculators can help: a budgeting calculator, a credit card payoff calculator, and tools to see how a repayment plan on your reverse mortgage would actually affect your monthly cash flow.
Access

Document

These resources stay available after your session ends, since resolving a default with a loan servicer often takes more than one conversation. Come back to them as your situation changes.
Download
Need More Guidance?

Speak with a certified housing counselor.

Financial tools

Explore reverse mortgage estimates with guidance

Use our educational calculator to better understand how home value, available equity, interest rates, and loan costs may affect a reverse mortgage estimate. These numbers are examples only and should be reviewed with a certified housing counselor.

  • Smart Retirement Planning

    See how a reverse mortgage could impact your long-term financial security and provide extra cash flow when you need it most.
  • Clear Financial Insights

    Understand how much equity you can access and how it could supplement your retirement income.
  • Personalized Loan Estimates

    Get a tailored breakdown of potential loan amounts, interest rates, and repayment scenarios based on your home's value.
Explore Educational Calculator

Always Free

No Obligation

Confidential

For Educational Guidance

  • Estimated Home Value

    Based on market data
$425,000
Sample estimate - actual values vary

Estimated Available Equity

~$210,000

Estimated Monthly Payment Option

~$1,050

Interest Rate Range

6.5% - 7.2%
These are sample estimates for illustration only. Speak with a certified counselor for accurate figures based on your situation.
Want personalized guidance?

Speak with a certified housing counselor to review your situation, questions, and next steps.

Common questions

Default Prevention Counseling FAQs

Answers to the most common questions about reverse mortgage default and prevention.
What Is a Reverse Mortgage Default?

A reverse mortgage default happens when a borrower fails to meet a loan obligation: paying property taxes, maintaining homeowners insurance, keeping the property in reasonable condition, or living in the home as your primary residence. The rules are the same across HECM and proprietary reverse mortgage products. Missing an obligation doesn't foreclose your home by itself. It starts a process your servicer has to follow before foreclosure proceedings can even begin.

What Happens After a Reverse Mortgage Default Notice?

A reverse mortgage default notice means your servicer believes you haven't met a loan requirement: paying property taxes or homeowners insurance, maintaining the home, or living in it as your primary residence. Contact your servicer right away as the verified borrower of record, and speak with a HUD-approved housing counselor to find the options that keep you out of foreclosure.

Can Default Counseling Really Help Me Keep My Home?

Often, yes. Most reverse mortgage foreclosures over unpaid property taxes or insurance are avoidable, because HUD gives servicers loss-mitigation tools, like deferral and repayment plans, specifically so they don't have to foreclose. Your counselor helps you use those tools instead of letting the default sit until foreclosure is the only option left.

What Documents Do I Need for Default Counseling?

Have your reverse mortgage statement available, any default or delinquency notices from your lender, property tax bills, homeowners insurance documentation, and recent income or financial records. Your counselor will guide you on exactly what is needed.

Is Default Counseling Confidential?

Yes. Credit.org is an independent nonprofit with no lender affiliation and no sales pressure, so nothing you tell a counselor gets reported back to your servicer. Your session is private.

How Much Does Default Counseling Cost?

Most reverse mortgage default counseling services are provided at no cost through our nonprofit mission. If a fee applies to a specific service, fee waivers may be available for individuals who qualify. Our goal is to help homeowners find solutions, not create additional financial burdens.

What Happens to a Non-Borrowing Spouse If the Borrower Dies or Moves Out?

If you're on the home's title but not on the reverse mortgage loan itself, you're a non-borrowing spouse, and the loan can become due when the borrower dies or permanently leaves the home. Loans originated after August 2014, HECM and proprietary reverse mortgage loans alike, include a Deferral Period that lets an eligible non-borrowing spouse stay in the home for life, as long as you keep paying property taxes and insurance, maintain the home, live there as your primary residence, and file an annual certification. The loan balance keeps growing during the deferral just as it would for any borrower, so the home equity left for your heirs still shrinks over time. Older loans use a similar process called the Mortgagee Optional Election. Ask your counselor whether you qualify.

Can I Prevent Default Before It Happens?

Sometimes, before you ever close the loan. If a lender's financial assessment flags concerns about your ability to keep up with property taxes and insurance, HUD requires a Life Expectancy Set-Aside, money withheld from your own loan proceeds and used automatically to pay those bills for you. If your loan doesn't have one and you're worried about falling behind, ask your counselor whether a loan modification or new set-aside is possible.

Do not wait to get help.

Our certified housing counselors are ready to guide you through your options.

Take the next step

Protect your home.
Get expert help today.

Speak with a HUD-certified housing counselor for personalized default prevention guidance. No judgment, no lender pressure — just clear, honest answers from a nonprofit you can trust.

Private & Confidential

Educational Guidance

HUD-Approved Agency

No Lender Sales Pressure

50,000+
People helped yearly
Trusted guidance from certified housing counselors
50+
Years of experience
Helping homeowners make confident, informed decisions
4.9/5
Client satisfaction
Based on thousands of counseling sessions