Nonprofit

Bankruptcy Counseling

Certified

Understand What Qualifies You for Bankruptcy

Bankruptcy can wipe out unsecured debt or restructure it into a plan you can actually afford, but it's not automatic relief. A means test decides whether you qualify for Chapter 7 bankruptcy or need to file Chapter 13 instead, and every consumer bankruptcy case starts with required credit counselingbefore you can file. Our counselors go through your income, debts, and creditors with you, explainwhat the bankruptcy code actually requires for Chapter 7, Chapter 11, or Chapter 13, and help youdecide whether filing is the right move before you spend money on a filing fee you can't get back. Bankruptcy is one form of debt relief, and unlike a debt management plan or debt settlement, it goesthrough the courts and follows federal law rather than a negotiation with your creditors.

HUD-Approved Housing Counseling Agency

NFCC Member

501(c)(3) Nonprofit
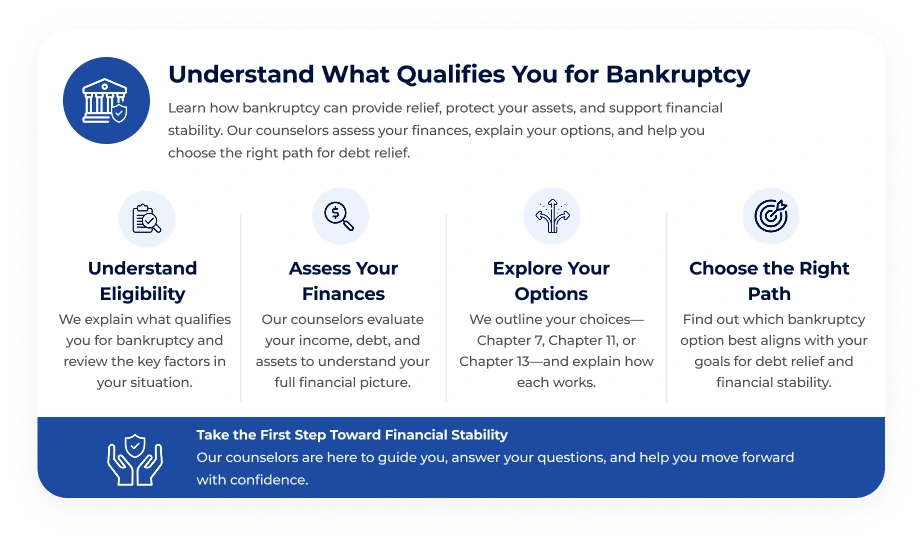
Bankruptcy counseling steps to assess eligibility, finances, and debt relief options.
Your options

What Bankruptcy Counseling Actually Covers

  • Bankruptcy counseling helps compare Chapter 7, 11, and 13 options.

    Identify Your Options, Make Informed Choices

    Chapter 7 bankruptcy can discharge most unsecured debt in a matter of months, but only if you passthe means test, and it can mean giving up property that isn't exempt under your state's rules. Chapter13 bankruptcy restructures what you owe into a three-to-five-year repayment plan and lets you catchup on mortgage arrears instead of losing your house. Chapter 11 is mostly for individuals whose debtis too high to qualify for Chapter 13 under the bankruptcy court's debt limits. Your counselor helps you see which one actually fits, and whether bankruptcy is even the most sensible debt relief optioncompared to what you've already tried.
  • Bankruptcy counseling helps protect essential assets and maintain financial stability.

    Protect Your Assets, Know Your Exemptions

    Bankruptcy law sets exemptions, atthe state or federal level, that determine whether you keep your car, your home equity, or your retirement account when you have secured debt tied to them. Filing also triggers an automatic stay, which stops most creditors from calling, suing you, or garnishing your wages on unsecured debt likecredit cards or medical bills the moment your case is filed. Your counselor walks through whichexemptions actually apply to you before you file.
  • Bankruptcy counseling resources to rebuild credit and improve financial stability.

    Rebuild Credit, Achieve Financial Stability

    A Chapter 7 bankruptcy filing can stay on your credit report for up to 10 years, and a Chapter 13 filingfor up to 7 (TransUnion), but your score usually starts recovering well before either one drops off. Wegive you a specific plan for rebuilding credit during that window instead of just telling you it will getbetter.
Your journey

Step-by-Step
Bankruptcy Counseling Process

  • Step 01

    Start With a Bankruptcy Counseling Session to Explore Options

    This first session is a free conversation about whether you should file bankruptcy at all. It's not thesame as the paid, legally required pre-filing credit counseling course you'll complete separatelybefore your case is filed.
  • Step 02

    Review Your Finances to Determine Bankruptcy Eligibility and Impact

    We'll run your income against your state's median, the same means test the bankruptcy court uses,to see whether you qualify for Chapter 7 or need to file Chapter 13 instead, and walk through whathappens to your secured debt and your unsecured debt under each one.
  • Step 03

    Understand Your Bankruptcy Filing Options and Legal Requirements

    Bankruptcy basics start here: what Chapter 7 and Chapter 13 actually discharge under federal bankruptcy law, what usually survives either one (child support, most student loans, and recent taxes), and the paperwork the bankruptcy court requires before you file.
  • Step 04

    Receive Resources to Rebuild After Bankruptcy and Regain Stability

    Completing debtor education isn't optional. The bankruptcy court won't grant your discharge withoutthat certificate. Once it's filed, we help you rebuild with a specific plan instead of general tips, starting the month your bankruptcy proceedings close, not years later.
  • Wherever You Are on Your Journey, We're Here to Help

No Obligation

No Pressure

Tools & resources

Bankruptcy  
Tools Made to Help You

The bankruptcy process runs on paperwork and deadlines, and most of the mistakes we see when people are filing bankruptcy come from skipping a step, not from the law itself: your pre-filing counseling certificate, your means test numbers, your post-filing debtor education certificate, all required under the bankruptcy code. These tools help you get each one right, on time, so a paperwork mistake doesn't delay your discharge.

Pre-Filing Credit Counseling

Complete your required pre-filing credit counseling online, the certificate you must file with your bankruptcy petition. Our U.S. Trustee-approved course issues it for $45 per session.
Start Course

Pre-Discharge Debtor Education

Complete your required pre-discharge debtor education online. You won't receive your discharge without this certificate, and it's what finalizes your bankruptcy proceedings. Ours costs $35 per session.
Start Course

Financial Calculators

Compare bankruptcy scenarios, evaluate Chapter 7 vs. Chapter 13 impacts, and calculate debt payoff timelines before filing.
Calculator

Consumer Bankruptcy Resources

Download step-by-step guides, checklists, and worksheets to organize your bankruptcy forms and documents, prepare for filing, and track your progress.
Access
Understand Your Bankruptcy Options

Explore resources that explain bankruptcy law in plain terms, then talk to a counselor about which chapter actually fits your debts, and whether bankruptcy is the right debt relief option for you.

Financial tools

Explore reverse mortgage estimates with guidance

Use our educational calculator to better understand how home value, available equity, interest rates, and loan costs may affect a reverse mortgage estimate. These numbers are examples only and should be reviewed with a certified housing counselor.

  • Smart Retirement Planning

    See how a reverse mortgage could impact your long-term financial security and provide extra cash flow when you need it most.
  • Clear Financial Insights

    Understand how much equity you can access and how it could supplement your retirement income.
  • Personalized Loan Estimates

    Get a tailored breakdown of potential loan amounts, interest rates, and repayment scenarios based on your home's value.
Explore Educational Calculator

Always Free

No Obligation

Confidential

For Educational Guidance

  • Estimated Home Value

    Based on market data
$425,000
Sample estimate - actual values vary

Estimated Available Equity

~$210,000

Estimated Monthly Payment Option

~$1,050

Interest Rate Range

6.5% - 7.2%
These are sample estimates for illustration only. Speak with a certified counselor for accurate figures based on your situation.
Want personalized guidance?

Speak with a certified housing counselor to review your situation, questions, and next steps.

Common questions

Bankruptcy FAQs

Answers to the most common questions about bankruptcy counseling.
Is Credit.org Approved by U.S. Trustees?

Yes. Credit.org is approved to issue Pre-filing Credit Counseling and Pre-discharge Debtor Education certificates in compliance with the bankruptcy code. Approval does not endorse or assure the quality of an agency's service.

Do I Need to See an Attorney Before My Session?

No. You're welcome to speak with a certified credit counselor at any point, before or after consulting an attorney.

How Soon Can I Schedule a Counseling Appointment?

You can skip the wait. Call us at 888-425-3453 during business hours and you'll speak with a certified counselor right away, no appointment needed.

How Long Is a Bankruptcy Counseling Session?

Most sessions take up to 90 minutes, depending on your situation, questions, and the info you provide. We'll guide you through every step.

What Documents Do I Need to Bring to My Bankruptcy Counseling Session?

Bring a list of all debts, recent pay stubs, tax returns, bank statements, and any legal notices you have received. Your counselor will guide you on additional documents needed for your specific situation.

Can I Complete Bankruptcy Counseling Online?

Yes. We offer convenient online pre-filing credit counseling and pre-discharge debtor education sessions that you can complete from home at your own pace.

What Happens to My Creditors When I File for Bankruptcy?

Filing your bankruptcy petition triggers what the bankruptcy code calls an automatic stay, and it takes effect immediately, without a judge having to approve anything first. Once it's in place, creditorsgenerally can't keep calling you, file or continue a lawsuit against you, or garnish your wages. The stay isn't unlimited, a few actions like certain child support proceedings aren't covered, and it can belifted early in specific situations, but for most unsecured creditors it's the main reason people say bankruptcy finally gave them room to breathe.

Still have questions?

Speak with a certified counselor about your bankruptcy options.
Take the next step

Ready to take control of

your finances?

Unbiased, confidential counseling from certified experts.

Private & confidential

Educational guidance

HUD-approved agency

No sales pressure

50,000+
People helped yearly
Trusted guidance from certified housing counselors
50+
Years of experience
Helping homeowners make confident, informed decisions
4.9/5
Client satisfaction
Based on thousands of counseling sessions