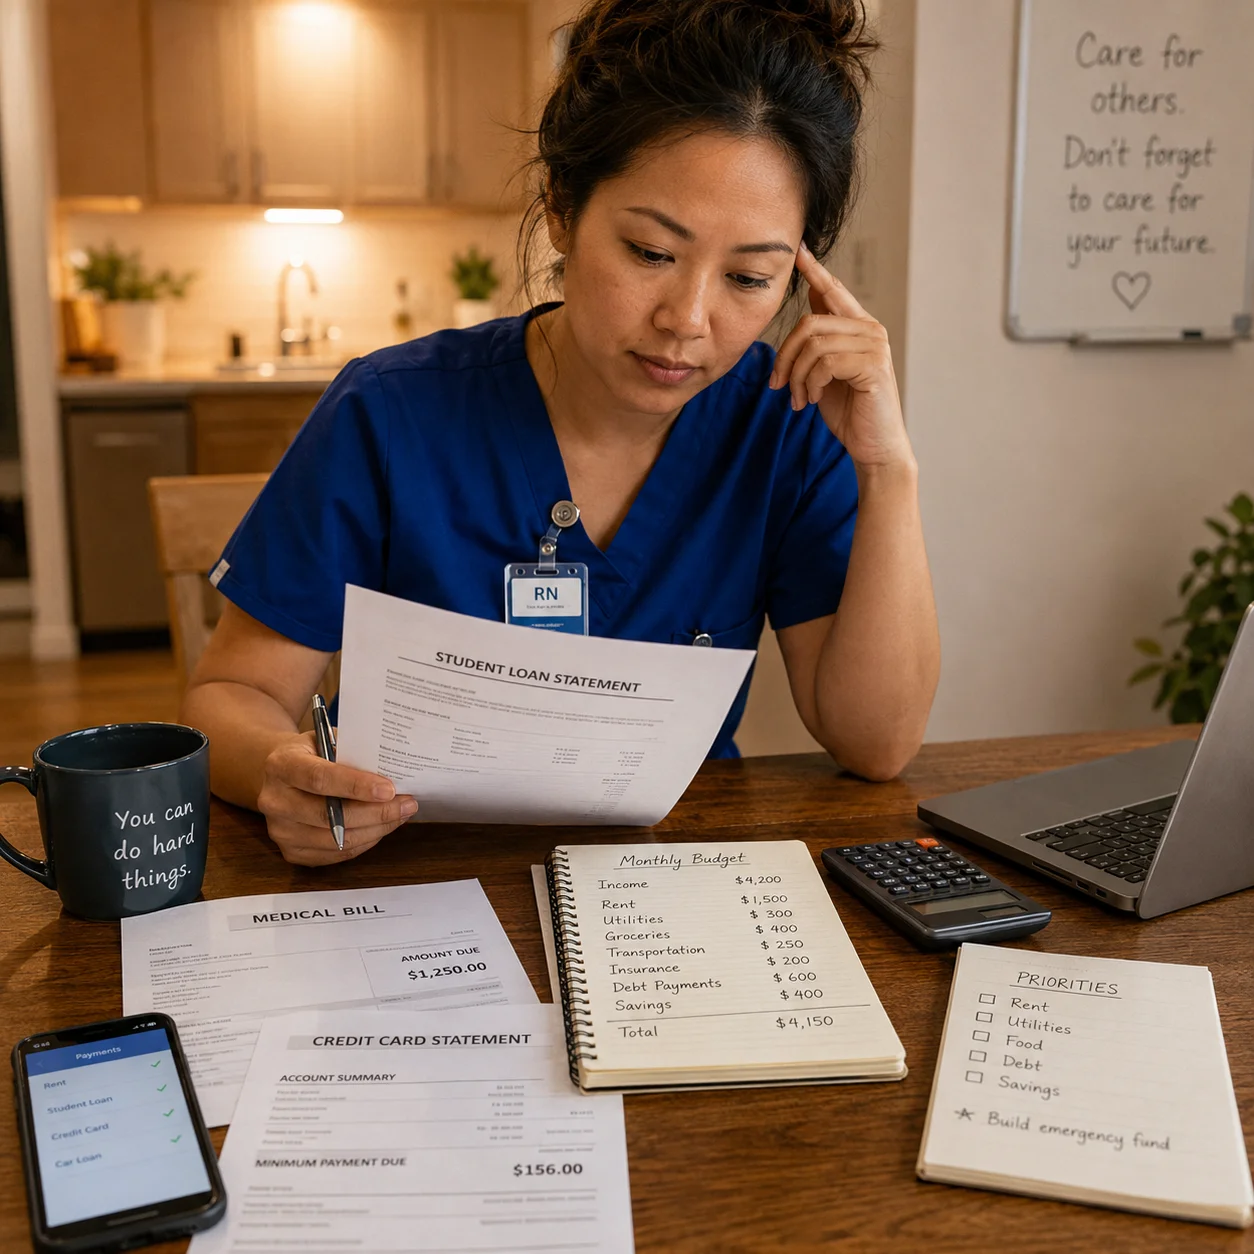
Healthcare workers are often told to wait for the next raise, the next credential, or the next job change to fix their finances. That is not a plan. If the current debt payments do not fit the current income, financial counseling should start with today’s budget, not a future salary.
Nurses, medical assistants, technicians, nurse practitioners, residents, public health workers, and other healthcare professionals can face the same financial hardships as anyone else. Student loans, medical bills, housing costs, credit cards, child care, and family obligations can pile up even when the work is steady.
Financial assistance can help with a specific need, such as medical expenses, housing, disaster recovery, or educational debt. A budget plan is different. It looks at the whole financial picture: income, payments, debt, savings, insurance, housing, and monthly costs.
Both can matter. A grant or assistance program may give short-term relief, but it will not fix a budget where debt payments are too high every month. That is where nonprofit financial counselors can help.
Credit.org’s guide on when to consider debt counseling explains when outside help makes sense.
Some financial assistance program options are tied to employment, location, or profession. Healthcare workers in underserved areas may qualify for loan repayment programs through federal or state programs. HRSA says its health workforce loan repayment programs repay part of qualifying educational debt in exchange for service at an eligible health care facility in a community in need.
Some professional associations, hospitals, and employers also offer emergency hardship funds, employee assistance programs, or short-term support for eligible applicants. These programs usually require documentation, such as proof of employment, income, expenses, account statements, or a hardship letter.
Do not assume every advertised program is legitimate or open to you. Check the criteria, contact the organization directly, and avoid any company that promises fast forgiveness or asks for upfront fees.
Medical student loan debt and nurse student loan forgiveness questions are common. Some healthcare workers may qualify for Public Service Loan Forgiveness if they have eligible federal loans, make qualifying payments, and work full time for a qualifying government or nonprofit employer. Use the official StudentAid.gov PSLF Help Tool to check your situation.
Public service loan forgiveness for doctors, nurses, and other healthcare workers depends on the loan type, repayment plan, employer, and payment history. Do not rely on social media claims or unofficial debt relief ads. If a forgiveness program sounds too easy, verify it through StudentAid.gov before you act.
Credit.org’s article on what happens if you default on a student loan can help if payments are already behind.
Healthcare workers can have medical bills too. If you are unable to pay a hospital bill, ask about charity care or a hospital financial assistance policy. USA.gov explains that charity care may help with medical bills after insurance or Medicaid has been applied. The CFPB also describes charity care as free or discounted health care for people who need help paying medical bills.
Tax-exempt hospitals are required to have written financial assistance policies. The IRS says these policies explain who is eligible, what help is available, and how patients can apply.
Ask the hospital billing office for the financial assistance application, required documentation, deadline, and appeal process. Do this before the account goes to collections if possible.
Start With the Bills Due Before the Next Paycheck
Financial wellness for healthcare workers does not start with a perfect spreadsheet. It starts with knowing what has to be paid before the next paycheck.
Begin with:
Then list credit cards, personal loans, medical debt, and other unsecured debt. Credit.org’s essential household budgeting tips can help you sort needs from optional spending.
Healthcare schedules can make this harder. Overtime, shift differentials, part-time hours, and second jobs may change monthly income. Build the budget around reliable income first. Extra pay should help reduce debt or build savings, not hide a payment plan that is too expensive.
Debt help for healthcare workers should not depend on a promised bonus, future raise, or forgiveness program that may not materialize. Start with the debts that are already due.
Credit.org’s guide to debt repayment and doing the math can help you compare payoff options. A nonprofit credit counselor can also review your income, expenses, credit card balances, interest rates, and monthly payments.
If unsecured debt is hard to manage, a debt management plan may help eligible consumers make one monthly payment toward participating debts. This is not a debt consolidation loan. You are not borrowing new money to pay old debt.
Be careful with debt relief companies that promise quick results. The FTC warns that scammers may demand upfront fees, guarantee fast debt settlement, or promise loan forgiveness that they cannot deliver.
Healthcare worker burnout is often discussed as a workplace issue, but money stress can make it worse. Debt, late bills, medical expenses, and student loans can follow someone home after every shift.
Financial counseling does not replace mental health care. If stress, anxiety, depression, or burnout are affecting your health or safety, contact a qualified mental health professional, employee assistance program, or crisis resource. For the money side, a counselor can help turn a pile of bills into a plan.
Start with the bill that is causing the most damage. If it is a hospital bill, ask about charity care. If it is student loan debt, check official federal repayment options. If it is credit card debt, talk with a nonprofit credit counselor before missed payments turn into collections.
If debt payments are the issue, Credit.org can help you review your options. Start with debt relief and counseling services.